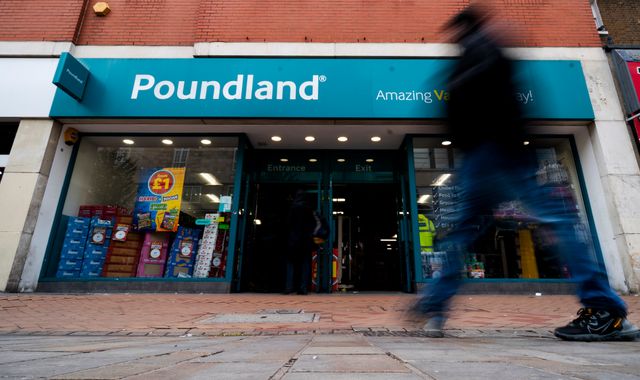
Poundland's owner has cashed in close to £20m in fees and interest payments from the discounter during its brief stint as its owner - and could stand to gain millions more from its collapse.
Sky News can reveal this weekend that the government has been informed that Gordon Brothers has received £18.3m as the majority owner of Poundland, which it only agreed to buy in June of last year.
The disclosure, just days before Poundland faces collapsing into insolvency proceedings, putting more than 10,000 jobs at risk, will pile pressure on executives at the US-based investment firm to agree a going concern sale of the business.
Gordon Brothers is due to face MPs on the business and trade select committee next Wednesday - in a session that will be held in private amid last-ditch talks with potential buyers.
Martin Property Group, a Northern Irish company, has been trying to buy Poundland solvently for weeks, but has seen its fully funded proposals rejected by Gordon Brothers.
A government source briefed on a presentation made on Wednesday by Poundland's bosses to Kate Dearden, the business minister, said it had shown the extent to which Gordon Brothers has already profited after acquiring one of Britain's biggest retailers for just one euro.
According to the Whitehall insider, Gordon Brothers has been paid £8.6m in interest, £3.8m in store closure fees and £2.6m in debt arrangement fees.
The remainder of the £18.3m comprises a miscellany of other fees and charges.
Poundland could not be reached for comment on the presentation made to the government.
In response to an emailed question about whether the firm would disclose how much it had received during its 17-month tenure as Poundland's owner, a Gordon Brothers spokesperson replied, saying it had "not publicly disclosed any financial information regarding Poundland as there is an ongoing sale process as well as [a notice of intention to appoint administrators] in effect".
A £30m shareholder loan - £22.5m of which is owed to Gordon Brothers - has been the focal point of the owner's reluctance to agree a solvent sale of the company to date.
Gordon Brothers acquired the loan for a nominal sum, with Pepco Group, the minority shareholder, offering to defer receipt of its £7.5m share of the loan if a solvent sale can be achieved.
It can also be revealed that in its capacity as administrator-in-waiting, AlixPartners has requested proposals from potential liquidators of Poundland's stores and stock in the event that a going concern deal cannot be secured.
This would earn millions of pounds more in fees for whichever firm was appointed as liquidator - with Gordon Brothers expected to be in the frame for the role unless it decided to recuse itself amid the intense acrimony over its ownership.
This weekend, there were indications that Gordon Brothers' stance towards a solvent sale may be softening amid one of the most politically fraught corporate crises in Britain since Labour came to power.
Andy Burnham, the prime minister, has waded into the row, while Jonathan Reynolds, the business secretary, this week held emergency talks with Gordon Brothers executives.
Mr Reynolds is said to have received assurances that Gordon Brothers was trying to deliver a solvent sale.
Gordon Brothers' UK operations are run by Mark Newton-Jones, the former Mothercare chief executive.
Read more:
Poundland owner seeks private MP session 'to avoid show trial'
Poundland owner turns to Thames Water creditors' lobbying firm
One insider said that a notice of intention to appoint administrators, which expires on Thursday, was likely to be extended.
Alternatively, Gordon Brothers could choose to allow the notice to lapse and continue as owner of the business during the crucial Christmas trading period.
Gordon Brothers is facing intense scrutiny over its stewardship of the chain after it emerged that it had frozen executives' access to Poundland's bank accounts and asset-based lending (ABL) facility.
The row has become particularly fraught because Poundland's trading performance has improved markedly under managing director Barry Williams and is profitable on an earnings before interest, tax, depreciation and amortisation basis.
Another potential buyer, Xyra Group Holdings, is reported to be interested in a solvent deal but has yet to sign up financial backers.
If Poundland does go bust, a break-up would take place with several hundred of the chain's stores being sold to other retailers.
Gordon Brothers' only meaningful public statement on the crisis came this week.
"When Gordon Brothers acquired the business, it was in distress and required a radical restructure, urgent operational change and significant funding, which we provided to support the company's ability to trade," the firm said.
"In spite of our efforts and the tremendous efforts of management to deliver a turnaround, the business remains challenged and vulnerable to any potential downturn in future trading.
"Our intent throughout the comprehensive sale process has been to protect as many jobs as possible and preserve value in order to deliver the best available outcome for the people, creditors and local communities who care about this business as much as we do."
(c) Sky News 2026: Revealed: Poundland owner's £18m bonanza from struggling discounter
 Deep forces are reshaping America's electoral map - and what it means for the 2028 presidential election
 Meghan's father Thomas Markle appears in court charged with possessing child abuse material
 Critical incident declared in Swansea after car 'damaged by gunfire' - with two arrested